Society
Metro Women’s Income Goes Into Lifestyle, Smaller-City Women Lead in Stock-Market Investment
Women’s Investment in the Stock Market: Smaller States Leave Metropolises Behind.
Women’s investment in the Indian stock market has been steadily increasing. According to NSE data, women now constitute nearly 25 percent of individual investors. Yet, more revealing than the national average is the geographical pattern underlying this investment.
In Goa, women account for 33.2 percent of investors, followed by Mizoram at 32.5 percent, Chandigarh at 32.4 percent, and Sikkim at 31.4 percent. Delhi, too, stands at around 30 percent. In contrast, the proportion is approximately 19 percent in Uttar Pradesh, 17 percent in Bihar, 18.5 percent in Tripura, and around 17 percent in Jammu and Kashmir.
This divergence raises a significant economic question: Why are women in smaller states moving ahead of women in several larger states and metropolitan centres in their investment in the stock market?
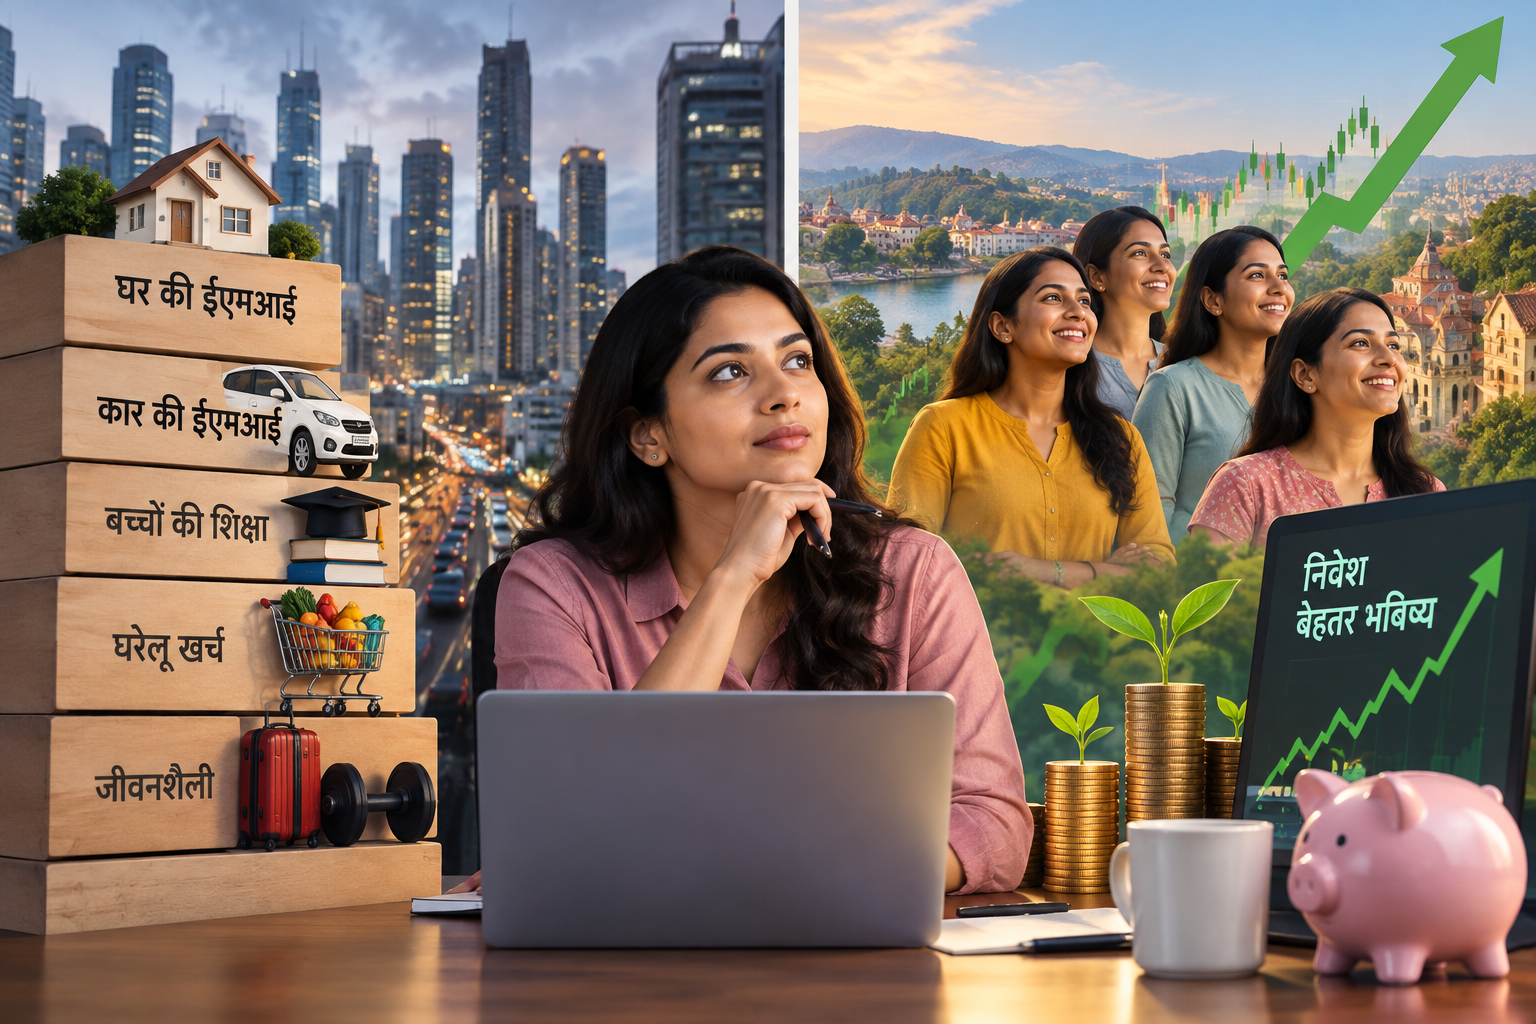
The answer cannot be explained by income alone. Women in metropolitan centres may have higher earnings, but those earnings are also subject to a greater number of pre-committed financial obligations. Home loans, car loans, children’s education, and lifestyle expenditures often determine a substantial portion of a household’s monthly cash flow even before discretionary financial decisions are made.
Consider a simple illustration. If a woman earns 1 lakh rupees a month and the family pays 40 thousand rupees towards a home loan and another 15 thousand rupees towards a car loan, 55 thousand rupees of her monthly income has already been structurally committed. If another 20 thousand rupees goes towards children’s education and other household expenses, and 15 thousand rupees towards travel, healthcare, and lifestyle expenditure, only 10 thousand rupees remains at the end of the month. In other words, out of an income of 1 lakh rupees, merely 10 percent remains available for investment at her own discretion.
The issue, therefore, is not merely how much one earns, but how much of that income remains uncommitted after the claims of contemporary consumption have been satisfied.
This is perhaps the most consequential financial implication of equated monthly instalments. A portion of today’s income becomes committed expenditure for several years into the future. In metropolitan economies, rising incomes are often accompanied by an expanding lifestyle architecture, which can, at times, take precedence over the accumulation of financial assets.
It is in this context that the data from smaller states becomes particularly significant. If a larger proportion of women, despite relatively limited incomes, are investing in the stock market, it raises the possibility that a greater share of household savings is being directed towards the creation of financial assets rather than being absorbed by consumption or debt servicing.
The significance of this trend, therefore, extends well beyond the narrative of women’s investment in the stock market. It offers a window into the changing architecture of household financial priorities. The real question surrounding the economic independence of the Indian woman is no longer simply how much she earns, but how much of what she earns, after the demands of EMIs and consumption, is ultimately converted into wealth for her future.